Showing posts with label Inheritance. Show all posts

Thursday, 17 January 2013

The Man Whose Birth Caused a Laugh


Isaac [Ī'zaac] he laugheth or laughing one. The son of Abraham and Sarah, who was born at Gerar when
Abraham as one hundred years of age and Sarah was about ninety years old (Gen. 17:19, 21;21:3-12; 22:2-9).

Isaac is one of the few cases in the Bible in which God selected a name for a child and announced it before he was born. In the Old Testament we have Isaac, Ishmael, Solomon, Josiah, Cyrus and Isaiah’s son; in the New Testament, John the Baptist and Jesus.

Isaac’s beautiful and suggestive name, “he laughed,” commemorates the two laughings at the promise of God—the laughing of the father’s joy and the laughing of Sarah’s incredulity which soon passed into penitence and faith (Gen. 21:6). Isaac was the child of the covenant, “I will establish My covenant with him.” To three patriarchs in succession was this covenant specifically given: to Abraham, as he left Chaldea (Gen. 12:3); toIsaac, when in Canaan during the famine (Gen. 26:4); toJacob, at Bethel (Gen. 28:14). Isaac, however, was the first to inherit the covenant, and to him God gave the whole inheritance of Abraham (Gen. 24:35).

Saturday, 12 January 2013

HEALING HOUSE: "I THOUGHT YOU WERE DEAD."

Tim Smith

Healing House is in Kansas City, Ks. It's a home for drug addicts started by a woman named Bobbie Jo. 

Bobbie Jo had been walking the streets for many years but then someone cared enough to share the Gospel with her and she was born again. At the same time, her mother died and left her an inheritance. She knew that many of the women who were drug addicts turned to the streets to support their habits. When they were arrested, put in jail and then released, they had no place to go. So they went back to working the streets. 

So with her inheritance, Bobbie Jo bought an old retirement home that was boarded up and rehabbed it. She invited the ladies to come and live there and as they did, she would share the Gospel with them. 

Thursday, 10 January 2013

The Year of the Lord’s Favor

Written by Barbara
“Remember me, O Lord, when you show favor to your people, come to my aid when you save them, that I may enjoy the prosperity of your chosen ones, that I may share in the joy of your nation and join your inheritance in giving praise.” (Psalm 106: 4-5)

Jesus said in Luke 4:18-19, “The Spirit of the Lord is on me, because he has anointed me to preach good news to the poor. He has sent me to proclaim freedom for the prisoners and recovery of sight for the blind, to release the oppressed, to proclaim the year of the Lord’s favor.” If you are a believer in the Lord, you have the right to be free from oppression. You have the right to be free from whatever holds you captive. You have the right to see, that which is unseen with eyes of faith. God does not want His children to remain captive to the things of this world. He sent Jesus to proclaim the year of the Lord’s favor.

Saturday, 15 December 2012

Ruth: Romance and Redemption

Ruth meets Boaz: Ruth 2
In Israel, the barley harvest began in the spring. The community in Bethlehem observed God’s law concerning harvesting: “When you reap the harvest of your land, do not reap to the very edges of your field or gather the gleanings of your harvest…. Leave them for the poor and the alien” (Leviticus 19:9-10).
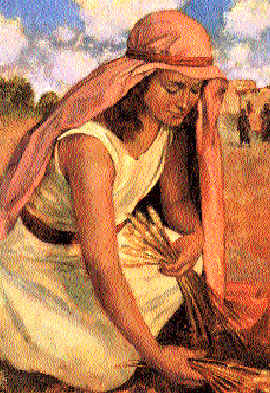
Ruth gleaning. By Dan Andreason
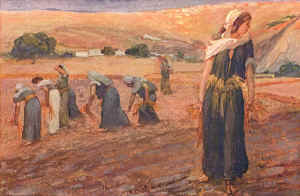
"And Ruth the Moabitess said to Naomi, ‘Let me go to the fields and pick up the leftover grain behind anyone in whose eyes I find favor’" (Ruth 2:2). Illustration above by Dan Andreason; below by James Tissot


Ruth and other gleaners.Ruth was both poor and an alien. She had few prospects in Judah, as Naomi had warned her. However, she was able to provide for Naomi and herself by working hard gleaning the grain left by the harvesters (Ruth 2:2).
There is an almost idyllic quality to the Bethlehem community described in Ruth, which — especially when one considers it existed during the turbulent period of the judges — testifies powerfully to the difference a few people living God’s way can make. Bethlehem would later become famous, first as the “town of David” and later as the birthplace of the Messiah (Luke 2:4-7).

“As it turned out, [Ruth] found herself working in a field belonging to Boaz, who was from the clan of Elimelech” (Ruth 2:3). Boaz was a “man of standing [Hebrew: ‘ish gibbor chail, implying Boaz was physically impressive and had noble character]” (verse 1).

Boaz asked his foreman who the stranger gleaning in the field was. The foreman replied that she was the young woman who had accompanied Naomi back from Moab. Boaz then told Ruth to continue gleaning in his field, and helped her far beyond the demands of the law. He even ordered his harvesters to make Ruth especially welcome, enabling her to gather extra barley.

Ruth then asked Boaz, “Why have I found such favor in your eyes that you notice me — a foreigner?” (verse 10). Ruth’s expression about finding favor in Boaz’s eyes, used by her on three occasions (verses 2, 10, 13), was a culturally appropriate way of showing respect. Ruth thus displayed the type of attitude the apostle Paul later taught Christians to have, when he said, “In humility consider others better than yourselves” (Philippians 2:3).

Saturday, 18 August 2012

See Yourself Risen With Jesus

"Constantly keep in mind Jesus Christ, the Messiah, [as] risen from the dead." (2 Timothy 2:8, The Amplified Bible)

This is the key to holding onto the blessings of God. When pressure comes, when troubles and trials are bearing down on you, remember Jesus Christ, risen from the dead!

Remember that when Jesus arose, you arose. When He came out of hell and defeated the enemy, you came out of hell and defeated the enemy. His victory is your victory because you're in Him.

In the hard places, remember that. When the devil tells you you're not going to get your answer this time, remember that. When he tells you there's no way out, you remember Christ, the Anointed One, the Victorious Conqueror, risen from the dead and seated at the right hand of the Father!

If there's an image Satan hates more than any other, it must be that image of Jesus, rising from the dead, stripping him forever of his authority, and openly displaying his defeat to all of heaven and hell. That's the picture you need to keep in the forefront of your mind. Think about it until it's etched into your heart so deeply that nothing Satan says or does can get it out of you.

That's when the gifts of God will be established in your life. That's when the devil won't be able to talk you out of your inheritance with trials and tribulations. Keep in mind Jesus Christ, risen from the dead!


Scripture Reading: Hebrews 12:1-13


Sunday, 12 August 2012

How Father God Feels About You

by Jack Hayford
How Father God Feels About YouThe story of the prodigal son, recorded in Luke 15, is often called the parable of the Father's heart. Jesus tells it, along with two other stories, not only in response to the seemingly "heart-less" religionists of His day, but also for you and me to know what is the Father's heart toward us.

Jesus tells of a man with two sons, one of whom asked for his inheritance in advance. The father gave it to him, and the son went out and squandered it, ending up in a pig sty. Finally, Scripture says, the young man "came to himself." He recognized the insensibility of the pathway he'd walked and how foolish he'd been to leave home. He returned, humbled, thinking he would ask to be just a servant at his father's place.

Friday, 25 May 2012

Three Relationships that Make Us Rich


Then one from the crowd said to Him, "Teacher, tell my brother to divide the inheritance with me."  But He said to him, "Man, who made Me a judge or an arbitrator over you?"  And He said to them, "Take heed and beware of covetousness, for one's life does not consist in the abundance of the things he possesses" (Luke 12:13-15).

This man came to Jesus to get him to "sort his brother out" over the inheritance, not realizing that his brother was the real treasure in his life - not the things he might inherit.

Here are three relationships that make us rich:

1.      Our relationship with God.  To know God makes you rich, no matter what material resources you may or may not have.

Some of those that the world would call rich are actually bankrupt when it comes to the most important treasure of all.

2.      Our relationship with others.  People, not things, are the real treasures in life.  I can honestly say that I am a rich man.  I have family and friends that I love and that love me. Things lose their meaning, and serve as a very poor substitute for relationships with people.

3.      Our relationship with our own heart.  Commune with your own heart… declares the psalmist in Psalm 4:4 (KJV).

That means hold some serious communication with your heart—get acquainted with your heart.  Don't let you and your own heart be strangers!

Wednesday, 25 April 2012

Press on in Patience


"...be not slothful, but followers of them who through faith and patience inherit the promises." (Hebrews 6:12)

You've been walking by faith. You've been believing God to meet your need. But what do you do when the results seem slow in coming and you are tempted to give up?

Be patient!

There is not much said about patience these days. But, when it comes to receiving from God, it is just as important as faith.

Monday, 16 April 2012

JOINT HEIRS WITH CHRIST

Matthew 12:50, "For whosoever shall do the will of my Father which is in heaven, the same is my brother, and sister, and mother." 

MATTHEW 12:46-50
We are not just heirs, we are joint-heirs with Christ. 


It would be wonderful to inherit any amount of God's glory and power. But, the idea that we share equally with the one who has inherited everything God is and has is beyond comprehension. This is an awesome blessing, but it also places a tremendous responsibility on us.
In the same way in which a check made out to two people cannot be cashed without the endorsement of both parties, so our joint-heirship with Jesus cannot be taken advantage of without our cooperation. 


Unaware of this, many Christians are just trusting that the Lord will produce the benefits of salvation for them. They are acutely aware that they can do nothing without Him, but don't realize that He will do nothing without us (Eph. 3:20).
The idea that God will do exceedingly abundantly above all that we ask or think, PERIOD, is not true. He has power, but it is the use of His ability combined with the power that works in us. "No power working in us" means no power of God will come through us. 


The exceeding greatness of His power that is to us-ward who believe is power that is not external, but is internal, within the believer. It is working according to the faith that we exercise in the indwelling Savior. It was this principle that Paul was stating when he declared, "I can do all things through Christ which strengtheneth me."
The way we place our endorsement on the check is to believe what God promised in His Word and act on it as if it were true. 


IT IS! Jesus has already signed His name to every promise in the Word. We aren't waiting for Him. He is waiting for us.
Andrew Wommack Daily Devotional

http://www.awmi.net/

Thursday, 12 April 2012

3 Critical Tools for Paying Off Debt

Written by Gary Foreman stretcher.com

This is the time of year when many people look at their debt situation and shudder. They dream of what it would be like to be out of debt. And, if they’re brave, they begin to plan a strategy to reduce the amount of debt they carry.

They’ll begin with high hopes. But many of them will quit before reaching their goal, disappointed, discouraged and defeated. Is there something that they could have done differently that would have given them a better chance at success? I think so.

You can find all kinds of advice about how to get out of debt. The web is full of the stuff. But, when you boil it all down, there are three things that form a foundation for a get out of debt effort.

1. Don’t expect immediate results. You won’t be getting out of debt in a matter of days or weeks. The only way to eliminate your debts quickly is to inherit a large sum of money, win the lottery or declare bankruptcy. The first two are unlikely. The third may remove debts quickly, but you’ll suffer with a lower credit score for years to come.
Recognize that it will probably take about as long to get out of debt as it took you to get into it. You can speed up the process but you won’t eliminate debt that took 10 years to accumulate in 10 months. You can shorten the time by being aggressive in your payback plan, but it still will be a long process.

What’s the take-away? You need to be prepared for a marathon race. This is not a sprint. If you’re prepared for the long haul you won’t be disappointed and discouraged when a year passes and you haven’t eliminated all your debts. You’ll expect a long battle and be ready to fight it.

2. You need a good plan. A good plan will stand the test of time. The longer you work with a good plan, the more you appreciate its usefulness. There are a number of good plans readily available. You may find that one is particularly well suited to your situation.

Any good plan will have a number of characteristics:


  1. It will include all your debts. That’s important to help you see the whole picture.
  2. It will help you evaluate exactly how bad your debt situation is. Not only will you know how much you owe, but you’ll know how much it’s costing you in interest each month/year.
  3. It will include a priority of which debts to pay off first – smallest to biggest? Highest to lowest interest rate?
  4. It will allow you to know how much money you’ll have each month to repay debts.
  5. It will free you from having decisions to make each month. You know how much money you’ll have and which debt is being reduced first. The decision is already made. It’s just a matter of executing your plan.
  6. It will allow you to calculate an approximate date that you’ll be debt free.
  7. It will help you monitor your progress. You should be able to predict where you’ll be 6 months from now. And, then compare your actual results to that prediction.
  8. It will take your personality into account. Some people need the motivation of seeing many small accounts being repaid quickly.
  9. Others are happier watching the average interest rate their paying decrease each month. A good plan will be tailored to your personality.
A good plan will do all those things. Some offer other bells and whistles. But any good plan should do all of the above things. If your plan doesn’t do them, keep looking for one that does. This job is hard enough with a good plan. Don’t weigh yourself down with a bad one.

3. Find a way to keep yourself motivated throughout the process. Once again, you’ll need to know what would encourage you when you’re thinking of quitting. For some people, rewards along the way work well. Perhaps a nice dinner or that coffee maker you’ve wanted would be a good reward when your car loan is repaid. Knowing that a reward is within reach could be enough to keep you going.

For others one big reward at the end is the best motivation. I know of people who’ve wanted to go on a cruise for years. They’ve added the cost of the cruise to their debts. And when it’s all paid off they’ll be packing their bags. To remind them now, they’ve posted pictures of cruise ships around the house as a continual reminder.

Getting out of debt is a tough challenge, but it’s a worthwhile one. And it’s one that you can accomplish with the right tools and sufficient determination!


Take the next step:
Managing debt starts with a plan
Digging out of debt 
Take a lesson: How to beat stress
http://powertochange.com/world/tools-for-paying-off-debt/

Thursday, 15 March 2012

Pity the Retirement Hoarder

By Joe MontStaff Writer | TheStreet.com

BOSTON (MainStreet) -- Few days pass without some new study or survey reinforcing a dire message that Americans are not saving enough for a comfortable retirement.
For some, that message may actually be detrimental. While true that many -- perhaps most -- are dangerously behind with their savings timeline, even those with a suitable nest egg are prodded continually into saving more. Some run the risk of saving too much, of letting their lives be dictated by compulsive frugality. Think of them as the financial equivalent of hoarders. They're so dead set on accumulation that they find it psychological torture to spend anything.
Some retirees could never spend all of their money, given their frugality, but still worry about running out of money or not having an inheritance to leave their children.
Ted Bovard, principal and financial consultant for Fort Pitt Capital Group in Pittsburgh, says his firm has high net worth clients who fall into this category. Even though they could never spend all of their money, given their frugality, they still worry about running out of money in retirement or not having an inheritance to leave their children.
As an example, one client, despite having a $9 million nest egg, called to seek advice on whether she could afford to buy a new clothes dryer.
"We have clients who have $6 million to $7 million saved and they ask, 'We were thinking about giving money away to this school, or this charity, or the grandkid -- do you think we can do it?' Well, how much money are you thinking of giving away? 'Probably just the gifting limit for the grandkids, maybe $13,000 times three or four.' Well, I think with $7 million you are OK," Bovard says.
"There is nothing wrong with being careful, but you can overdo it, says Peter D'Arruda, president ofCapital Financial Advisory Group in Cary, N.C. "It's like the skinny squirrel who stores a bunch of nuts in a tree over and over again, but doesn't eat them. He just runs off looking for more nuts. Then termites get in there and when squirrel comes back the tree's not there anymore."
D'Arruda uses that fable-like example to explain that the fear of depleting assets doesn't just lead investors to take on an unhealthy degree of risk; they can also err on the side of perceived safety.
The fear of running out of money isn't always without merit, he says, pointing to the "biggest risk of all" -- the eventual need for long-term care. With these needs in mind, he urges clients to create an income stream and hedge against future expenses with various annuity and life insurance policies that include long-term care riders. What he doesn't advocate is relying on so-called "safe" investments -- including cash, CDs and other bank products -- to provide peace of mind.
"CD accounts are not earning anything," D'Arruda says. "I refer to it as losing money safely. Look at inflation right now. You can go to the grocery store now and see how expensive it is, and there are also rising fuel costs and increasingly expensive health care. You need to be keeping up with inflation if you want to make sure you have money for the future."
Bovard sees several reasons for why some people have a hard time accepting that their savings are, in fact, sufficient. Factors include a lifetime of frugality, over-reacting to market fluctuations and the intangibility of wealth that is in investments, not in physical cash, gold or even stock certificates.
"A lot of time, I think I, as their adviser, am the person who can help them relax," he adds. "For the folks we have had longer-term relationships with, they look to you to tell them what they can do and what they can't do. If we tell them they can do it, they are more comfortable."
A challenge, he says, is getting clients to move past an all-encompassing drive to save and accumulate wealth and to focus as well on enjoying the fruit of their labor.
"People ask, 'How much do I need, do I have enough?' We don't really focus so much on the total number. We see how do you want to live and what it's going to cost," Bovard says. "If it is $500,000 a year, your $2 million isn't going to get you very far. If it is $50,000 a year then yes, you are probably going to be in very good shape."
A persistent voice warning that some are saving too much for retirement is Laurence Kotlikoff, an outspoken economics professor at Boston University.
In a past interview, Kotlikoff, who co-wrote the book Spend 'Til the End -- The Revolutionary Guide to Raising Your Living Standard, Today and When You Retire (Simon & Schuster, 2008) with Scott Burns, put much of the blame on the retirement calculators companies such as Fidelity, TIAA-CREF, Vanguard, Schwab and T. Rowe Price deploy on their Web sites.
"Financial advisers are giving bad advice using bad financial tools that aren't remotely capable of dealing with the question that they are trying to answer," he said, noting that advisers can profit from their inadequate assessments.
"The bottom line is that if you over-recommend products, you sell more," he said. "If you get compensated, either directly or indirectly, based on your sales, there is an incentive to make recommendations that are, on average, too high."
Kotlikoff, who has crafted his own retirement software tool, ESPlanner, estimates that about 20% of households are likely saving too much for retirement, compared with the 40% he believes are saving dangerously too little.
"I think under-saving is probably a bigger problem, but there is still a risk with over-saving," he said. "You could save like crazy and then you can drop dead when you hit 55. It is not only that you may die young, it is also that you can be induced into much riskier securities than you should be investing in because you think that this is the only way you can make your target. The whole focus is on making a target that is ridiculous to begin with."
Bovard says many retirees who have saved and invested appropriately throughout their life follow a similar pattern of financial realization.
They start out very nervous they don't have enough. That persists for the first seven years or so. Then they start to breathe a sigh of relief and get comfortable with the idea that they can enjoy life and spend down some of their assets. Later, they fully grasp that they have more money than they can ever spend and face regrets over what they wish they had done.
Bovard isn't surprised by the psychology at play among those who resist post-retirement spending.
"You spent 40 to 45 years accumulating this pot of money, and you did it by saving and saving and scrimping," he says.
In response, he tries to work with clients, especially during the early years of retirement, to "bump that expense level up a bit" and factor in the cost of various trips and activities they have expressed an interest in but haven't had the time to do until retirement.
"Sometimes part of our job is not just to be your financial adviser, but also a counselor," Bovard says. "It's all about striking a balance. If there are a couple of things you want to get done, lets figure out how to do them and still feel comfortable whether the markets are up or down or back and forth. While you still have the health and energy and desire, let's make these things you want to do happen."
"If you can't actually do that and relax, why retire? Maybe you are just tired of work, and that's fine, but if the idea is to retire because there are things you want to do and enjoy, then you are going to have to learn to relax a little bit," he adds. "It is a very different thought process for people when they've spent years pumping money in and now they turn around and have to take money out. Psychologically it is a huge transformation and if they are a workaholic, this can be a very difficult transition."
The balancing act between preserving financial security and enjoying your money differs from person to person, Bovard says. It is hardest for those he describes as "worrywarts."
"You have to deal with that personality differently, and they may never be comfortable," he says. "You say that they can afford to do something and they reply, 'Oh, I'd better not.' As soon as you go through the first downturn together -- and if you look at them long enough you are going to go through at least one or two or maybe three -- they are like, 'See, I knew it, I've got to pull back, I knew I shouldn't have gone on that trip.' What I have to say to them is that we've got the money set aside and life is going to move on whether the markets are up or down."
Bovard says having a solid financial plan in place helps investors learn to enjoy life in retirement. It also keeps them from taking on excessive risk in the name of returns.
"It's important to have the ability to stick to that plan through the good the bad and the ugly," he says. "It is not just when things are bad that people go off the reservation. When things are great, people believe they are much less risk averse. 'Oh look, everybody is making tons of money and I'm not making as much.' Well, remember that we have a balanced portfolio because when things are down you get really upset. We'll still get to the same place, we are just going to do it with less bumps."
--Written by Joe Mont in Boston.

Wednesday, 14 March 2012

Billionaire Says Her Kids Aren’t Fit for Inheritance


By Robert Frank | The Wall Street Journal 

If you ask the rich about the biggest problem created from their wealth, they will usually say their kids.

EPAMost of today’s self-made rich didn’t grow up with money (surveys show 75% of millionaires didn’t inherit their wealth). And today’s rich parents expect their kids to grow up with middle-class values– just as they did.


[More from WSJ.com: When Mom Goes Viral]

It’s a noble goal. But when those parents are flying the kids around on a private jet or giving them a Mercedes for their Sweet 16, it should come as no surprise that their kids lack the same work ethic and hustle as a middle-class kid.

And so wealthy parents today face an inevitable choice: leaving boatloads of money to kids who aren’t good with money.

Gina Rinehart, the Australian mining billionaire, has cracked open the debate with a strange court battle winding its way through the Australian legal system. In short, Ms. Rinehart inherited a mining empire from her dad. Her three kids were also left with a stake in the family trust. Yet Ms. Rinehart shut them out of their ownership stakes, and now the kids are fighting back.

[More from WSJ.com: Finding Food Allergy Allies]

Court documents cited in the Australian media show that Ms. Rinehart believed the kids weren’t fit to manage their fortune. She said none had ever held a real job, unless it was given to them by the family. “None of the plaintiffs (her children) has the requisite capacity or skill, nor the knowledge, experience, judgment or responsible work ethic to administer a trust in the nature of the trust in particular as part of the growing HPPL Group,” she claimed in court papers.

She added that the kids are “manifestly unsuitable” to manage the fund and that it would be in the “best interests of the beneficiaries to force them to go to work.”

[More from WSJ.com: Debt, the American Way]

Ms. Rinehart may well be right. But it raises a natural question: who raised these kids? And if Ms. Rinehart played a role, isn’t she basically using her own parenting as the reason to cut them out?

Granted, kids are only partially shaped by the parents. But for a rich parent to criticize their kids as lacking a work ethic seems, well, a bit rich.

[Related: Kids Are Genius!]
Do you think it’s fair for rich parents to criticize their kids for being spoiled?